Elearnmarkets - Financial Market Learning
  • Courses
  • Webinars
  • Stories
  • Language
    • English
    • Hindi
    • Bengali
No Result
View All Result
Get Free Course
  • Basic Finance
  • Derivatives
    • Futures
    • Options
  • Financial Planning
  • Fundamental Analysis
  • Technical Analysis
  • Mutual Funds
  • Marketshala
  • Miscellaneous
Elearnmarkets - Learn Stock Market, trading, investing for Free
  • Courses
  • Webinars
  • Stories
  • Language
    • English
    • Hindi
    • Bengali
No Result
View All Result
Get Free Course
Elearnmarkets - Learn Stock Market, trading, investing for Free
No Result
View All Result
Home Financial Planning Tax Planning
emergency fund

Emergency Fund Planning: How Much to Save and Where to Keep It in India

Vivek Bajaj by Vivek Bajaj
October 13, 2026
in Tax Planning, Financial Planning, Personal Wealth
Reading Time: 9 mins read
0
Share on FacebookShare on XShare on WhatsApp
Emergency funds are becoming essential in India as layoffs continue to hit salaried professionals, with fixed costs like rent, EMIs and insurance premiums carrying on after the paycheque stops. By calculating three to six months of essential expenses and parking the money in liquid funds, sweep-in FDs or high-interest savings accounts, investors can keep it safe, accessible and separate from long-term investments.
Table Of Contents
  1. What Is an Emergency Fund?
  2. Why Do We Need an Emergency Fund?
  3. How to Calculate Your Emergency Fund
  4. How to Actually Build It
  5. Where to Keep Your Emergency Fund
    • Liquid Funds: For Short-Term Parking
    • Sweep-In FD: For Automatic Savings
    • High-Interest Savings Accounts: For Easy Access
  6. Common Mistakes People Make With Their Emergency Fund
  7. Conclusion
    • FAQs

A sudden layoff can disrupt a person’s finances even when they have been earning a steady salary for years. Rent, home loan EMIs, groceries, and insurance premiums continue to demand attention, even after the monthly paycheck stops.

As per layoffs. fyi, recent tech layoffs as of 9th October are 131,687 tech employees and 318 tech companies.
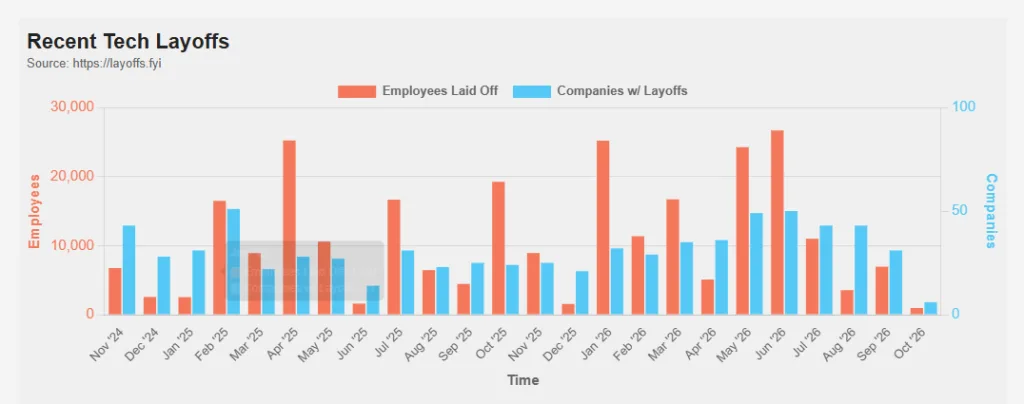
Tech layoff graph 2024 to 2026

An emergency fund helps you manage this uncertainty by covering essential expenses while you look for another job or deal with an unexpected bill. The commonly recommended target is three to six months of essential expenses, but the amount you need depends on your income stability, financial commitments, and dependants.

In this blog, we will discuss why an emergency fund in India matters, how much emergency fund you need, how to build it, and where to keep the money so it remains safe and accessible when you need it.

What Is an Emergency Fund?

It is money you set aside to cover unexpected expenses, such as a medical bill, sudden job loss, or urgent home or vehicle repair. It helps you manage these situations without taking a high-interest loan or selling your investments at an unfavourable time.

Unlike savings for a holiday or a new phone, it is reserved for genuine financial emergencies and should be kept somewhere you can access it when needed.

Why Do We Need an Emergency Fund?

  • To manage job loss: Finding a new job can take time, but rent, EMIs, and other essential expenses continue even when your salary stops.
  • To cover medical expenses: Your health insurance may not cover every treatment or expense, leaving you to pay some costs out of pocket.
  • To handle unexpected expenses: Urgent repairs, family emergencies, or sudden travel can disrupt your monthly budget if you do not have savings set aside.
  • To avoid high-interest debt: Having money available can reduce the need to rely on credit cards or personal loans during a financial emergency.
  • To protect your long-term investments: You can avoid withdrawing money from investments at an unfavourable time or interrupting savings meant for goals such as retirement or buying a house.

How to Calculate Your Emergency Fund

To work out how much emergency fund you need, start with these simple steps:

  1. Add up your essential monthly expenses: Include rent or home loan EMIs, groceries, utilities, insurance premiums, school fees, and minimum debt payments. Exclude discretionary expenses such as dining out, shopping, and entertainment.
  2. Calculate your target amount: Multiply your total essential monthly expenses by three to six months to estimate how much you need to save.
  3. Adjust based on your needs: Consider your income stability, dependants, and financial commitments. If your income is irregular, aim for a larger buffer to cover a longer period without earnings.

For example: If your essential monthly expenses are ₹30,000, your calculation would be:
  • Monthly essential expenses: ₹30,000
  • For 3 months: ₹30,000 × 3 = ₹90,000
  • For 6 months: ₹30,000 × 6 = ₹1,80,000

Therefore, your target would be ₹90,000 to ₹1,80,000, depending on your financial circumstances. You can also run the numbers through an emergency fund calculator to double-check your target.

How to Actually Build It

Building this safety net is easier when you treat it as a regular financial commitment rather than saving whatever is left at the end of the month. Build it with these three habits:

  • Automate your savings: Set up a fixed transfer to a separate account as soon as your salary or income arrives. Start with an amount you can comfortably afford, such as ₹5,000 or ₹10,000 a month, and increase it as your income grows.
  • Put extra income to use: Direct bonuses, tax refunds, or additional freelance earnings towards the fund instead of absorbing them into regular spending.
  • Keep the fund separate: Use an account dedicated to emergencies rather than your everyday spending account. This helps reduce the temptation to dip into the money for routine expenses.

Where to Keep Your Emergency Fund

Now, the main question is where to save it. There are three common options.

Liquid Funds: For Short-Term Parking

  • How they work: Liquid funds invest in short-term debt and money market instruments, making them an option for parking money you may need at short notice.
  • Access to money: Some fund houses offer instant redemption, subject to scheme eligibility and limits. Under the commonly applicable instant redemption facility, the amount is capped at the lower of ₹50,000 or 90% of the eligible investment per day. Other redemptions typically settle on the next business day, subject to applicable rules and cut-off timings.
  • Taxation: Gains from specified debt-oriented mutual funds acquired on or after 1 April 2023 are generally taxed at the investor’s applicable income tax slab rate under Section 50AA, subject to the relevant conditions.
  • Exit load: Some liquid funds charge an exit load for redemptions during the first seven days. Check the scheme’s terms before investing.
  • What to check: Before choosing among liquid funds, check the fund’s portfolio quality, expense ratio, exit load, redemption timelines and eligibility for instant redemption.

Sweep-In FD: For Automatic Savings

  • How they work: A sweep-in FD links your savings account to a fixed deposit. When your balance exceeds a specified threshold, the surplus is transferred into an FD, according to your bank’s rules.
  • Access to money: If your savings account balance falls short, the bank can automatically break the required portion of the FD to cover the shortfall.
  • Interest implications: Depending on the bank’s terms, the interest earned on the withdrawn portion may be affected, while the remaining deposit continues earning interest.
  • What to check: Sweep thresholds, deposit units, interest rates, premature withdrawal rules, and minimum balance requirements vary by bank. Review the terms of your specific account before setting up the facility.

High-Interest Savings Accounts: For Easy Access

  • How they work: Some small finance banks and other banks offer higher savings account interest rates than many traditional savings accounts.
  • Access to money: Funds can generally be accessed through transfers, debit cards, or UPI, without waiting for mutual fund redemption or breaking an FD.
  • Interest rates: Rates vary by bank, account balance, and applicable conditions. Check the bank’s current rate and eligibility requirements before opening an account.
  • Deposit safety: Eligible deposits at insured banks are covered by DICGC insurance up to ₹5 lakh per depositor per bank, including principal and interest, subject to the applicable rules.
  • What to consider: Compare the interest rate, withdrawal limits, minimum balance requirements, digital banking facilities, and deposit insurance coverage before choosing an account.

Common Mistakes People Make With Their Emergency Fund

  • Investing in equity: Keeping it in stocks or equity mutual funds defeats its purpose. Markets can fall unexpectedly, and you may be forced to sell your investments at a loss when an emergency arises.
  • Using it for planned expenses: Avoid dipping into it for planned expenses such as vacations, weddings, or a new phone. These should be covered by separate savings so that the money remains available for genuine financial emergencies.
  • Not replenishing the fund after use: Using it for a genuine emergency is exactly what it is meant for. However, once your financial situation stabilizes, start rebuilding the amount you have withdrawn to ensure you are prepared for the next unexpected expense.

Conclusion

The size of your emergency fund is a personal number, built from your own expenses and your own income stability, not a rule copied from a blog post. An emergency fund calculator can help you reach that number faster. Where you park it matters almost as much as how much you save, since the wrong choice can mean either losing access when you need it most or losing more to tax and low returns than necessary. Get both right, and the fund does the one job it exists for: sitting quietly, doing nothing, until the day it has to.

FAQs

1. Is a fixed deposit a good place to keep an emergency fund?

Yes. A sweep-in FD offers easy access to funds while earning FD interest. Regular FDs may involve penalties or delays for premature withdrawal.

2. Should I invest this money in mutual funds?

Liquid funds can be an option for short-term parking, but they carry some risk. Avoid equity and hybrid funds, as market fluctuations can reduce your savings when you need them.

3. How is an emergency fund different from a sinking fund?

It covers unexpected expenses, such as medical bills or job loss. A sinking fund covers planned expenses, such as vacations or annual insurance premiums.

4. Can I use this money for planned expenses?

It is best to avoid this. Set aside money separately for planned expenses so the money remains available for genuine emergencies.
Tags: advancebasiccandlestick patternemergency fundsintermediatestock market
ShareTweetSend
Previous Post

RBI’s New FD Interest Rate Rules From 1 October 2026: What Changes for You

Vivek Bajaj

Vivek Bajaj

Mr Vivek Bajaj has over 20 years of experience in Multi-Asset Trading, Momentum Investor and student of Mark Minervini. He is the co-founder of StockEdge and Elearnmarkets and is passionate about data, analytics, and technology. He serves on various exchange committees and has played a significant role in the evolution of India's derivative market. He has been a speaker at various colleges and higher institutions, including IIT and IIMs.

Related Posts

How to invest in real estate in India guide
Financial Planning

You Don’t Need to Buy a House to Invest in Indian Real Estate Anymore

August 27, 2026
104
Reasons for debt
Budgeting & Savings

5 Common Reasons People Get Into Debt

June 23, 2026
255
what are value funds
Financial Planning

What Are Value Funds? Strategy, Benefits & Risks

April 14, 2026
333
Overnight funds
Personal Wealth

What Is an Overnight Fund? Meaning, Benefits, and How To Invest

March 13, 2026
137

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Disclaimer

Elearnmarkets (StockEdge Fintech Private Limited – formerly known as Kredent InfoEdge Private Limited) is a SEBI-registered Research Analyst (RA) entity (SEBI Registration No.: INH300007493). The information provided in this article is for educational and informational purposes only and should not be considered as an offer to buy or sell any securities or investment products.

The stocks, securities, and investment instruments mentioned herein are not recommendations under SEBI (Research Analysts) Regulations, 2014. Readers are advised to conduct their own due diligence and seek independent financial advice before making any investment decisions.

Investments in securities markets are subject to market risks. Please read all related documents carefully before investing. Investing in Equity Shares,
Derivatives, Mutual Funds, or other instruments carry inherent risks, including potential loss of capital. Elearnmarkets (StockEdge Fintech Private Limited – formerly known as Kredent InfoEdge Private Limited) does not provide any guarantee or assurance of returns on any investments. Past performance is not indicative of future performance.

Elearnmarkets Logo

Follow Us

Facebook-f X-twitter Instagram Linkedin-in Youtube Telegram

Register on Elearnmarkets

Continue your financial learning by creating your own account on Elearnmarkets.com

Register Free Account

Download App

Playstore logo
Download on app store

Categories

  • Basic Finance
  • Derivatives
  • Financial Planning
  • Fundamental Analysis
  • Technical Analysis
  • Mutual Funds
  • Miscellaneous

Popular On Elearnmarkets

  • Market Superheroes:
  • Vivek Bajaj
  • Chetan Panchamia
  • Ashish Kyal
  • Premal Parekh
  • Abhijit Paul
  • Jegan
  • Sivakumar Jayachadran
  • Jyoti Budhia
  • Vivek Gadodia
  • Vishal Mehta
  • Piyush Chaudhry
  • Santosh Pasi
  • Gomathi Shankar
  • Market Superheroes:
  • Vivek Bajaj
  • Chetan Panchamia
  • Ashish Kyal
  • Premal Parekh
  • Abhijit Paul
  • Jegan
  • Sivakumar Jayachadran
  • Jyoti Budhia
  • Vivek Gadodia
  • Vishal Mehta
  • Piyush Chaudhry
  • Santosh Pasi
  • Gomathi Shankar
  • Courses:​
  • Options Trading
  • Dow Theory
  • Momentum Trading
  • Stock Investing
  • Harmonic Chart Patterns
  • Algo Trading
  • Elliot Wave Theory
  • Advanced Excel
  • Cryptocurrency
  • NSE Certification Course
  • Courses:​
  • Options Trading
  • Dow Theory
  • Momentum Trading
  • Stock Investing
  • Harmonic Chart Patterns
  • Algo Trading
  • Elliot Wave Theory
  • Advanced Excel
  • Cryptocurrency
  • NSE Certification Course
  • Webinars:
  • Bank Nifty Scalping
  • Intraday Trading Strategies
  • Options Trading Strategies
  • Options selling
  • Price Action
  • Relative Strength
  • Tax Planning
  • Options Buying
  • Growth Stocks
  • Portfolio Management
  • Risk Management
  • Renko Charts
  • Crude Oil
  • Traders Psychology
  • Moving Average
  • Multibagger Stocks
  • Free Learning Modules:
  • Intraday Trading
  • Options Scalping
  • Swing Trading
  • Financial Modelling
  • RSI Indicator
  • Bollinger Bands
  • Pricing of Futures
  • Personal Finance
  • Initial Public Offerings (IPO)
  • Value Investing
  • Technical Indicators
  • Candlesticks
  • Chart Patterns
  • Option Greeks
  • ELSS Funds
  • Banking and Insurance
  • Real Estate
  • Gold
  • Book Summaries:
  • Rich Dad Poor Dad
  • Psychology of Money
  • The Intelligent Investor
  • The Richest Man in Babylon
  • Think and Trade Like a Champion
  • Value Investing and Behavioural Finance
  • Trading in the Zone
  • Learn to Earn
  • Book Summaries:
  • Rich Dad Poor Dad
  • Psychology of Money
  • The Intelligent Investor
  • The Richest Man in Babylon
  • Think and Trade Like a Champion
  • Value Investing and Behavioural Finance
  • Trading in the Zone
  • Learn to Earn
  • Tools:
  • CAGR Calculator
  • SIP Calculator
  • eLearnOptions
  • Future Value Calculator
  • Present Value Calculator
  • Atal Pension Yojana
  • Cost of Delay Calculator
  • Become a Crorepati
  • Tools:
  • CAGR Calculator
  • SIP Calculator
  • eLearnOptions
  • Future Value Calculator
  • Present Value Calculator
  • Atal Pension Yojana
  • Cost of Delay Calculator
  • Become a Crorepati

© 2026 Elearnmarkets. All Rights Reserved

  • Visit Elearnmarkets
  • Courses
  • Webinars
  • Financial Guides
  • Get Free Counselling
  • Visit Elearnmarkets
  • Courses
  • Webinars
  • Financial Guides
  • Get Free Counselling

Download Our App

Deliver breaking news, insightful commentary, and exclusive reports. Targeting readers who rely on our platform to stay ahead.

Contact Benzinga
No Result
View All Result
  • Article Categories
    • Basic Finance
    • Derivatives
    • Financial Planning
    • Fundamental Analysis
    • Technical Analysis
    • ETFs & Mutual Funds
    • Marketshala
    • Miscellaneous
  • Language
    • Hindi
    • Bengali
    • English
  • Courses
  • Webinars
  • Stories
Get Free Course

© 2024 Elearnmarkets All Rights Reserved

Guide to Basics of Stock Investing
Learn to interpret the financial performance and health of a company.
Download Guide For FREE
Guidebook on Savings and Investment
A comprehensive guide book to start your investment journey
Download Guide For FREE